
DSCR loans
The loan most real estate investors start with. Qualify an investment property on the rent it produces, not your personal income. In most cases no tax returns or W-2s are required, and the property can close in your LLC.
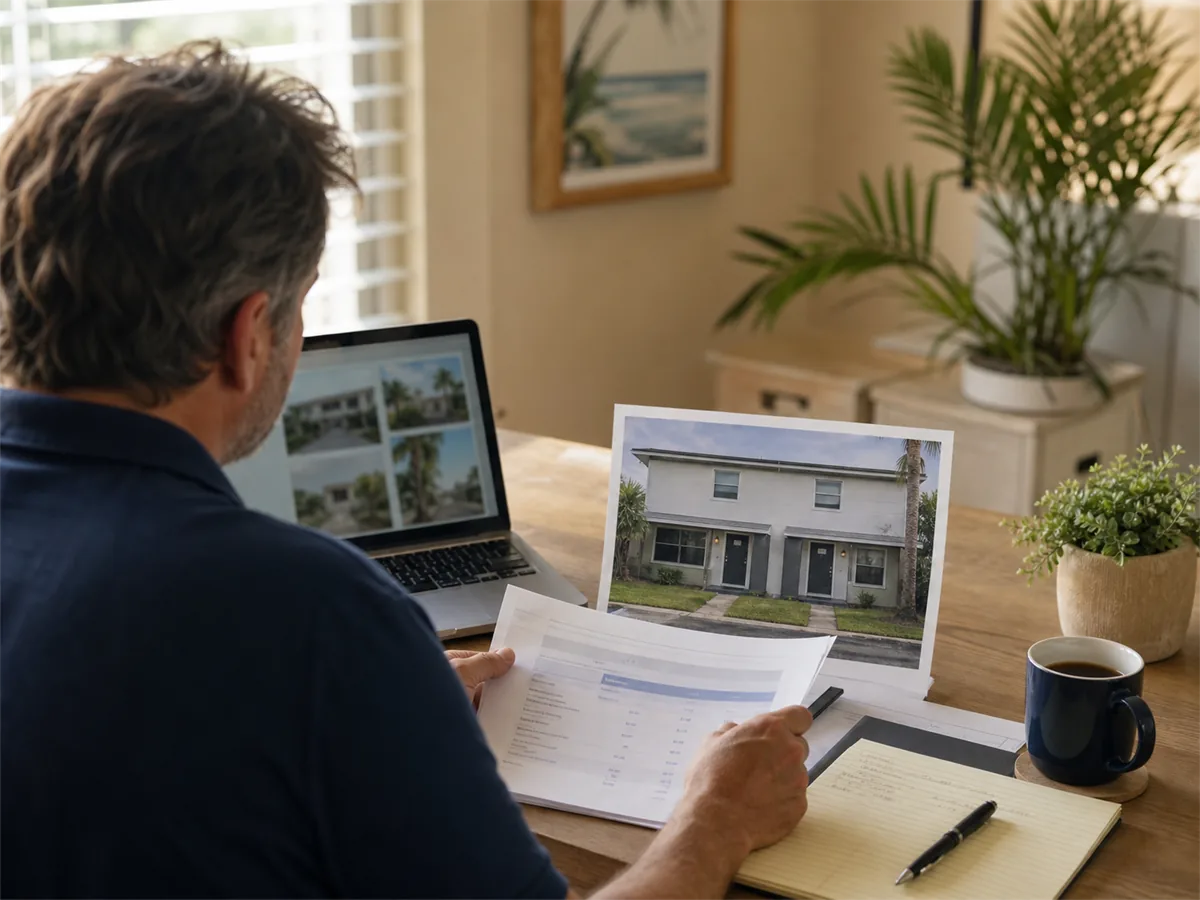
Is a DSCR loan
right for you?
DSCR stands for debt service coverage ratio: the property’s rent measured against its monthly payment. If most of these sound like you, it is worth a conversation.
- You are buying or refinancing a rental property, not a home you will live in.
- You want to qualify on the property’s rent, not tax returns or W-2s.
- You hold, or plan to hold, the property in an LLC or other entity.
- Your tax returns understate the cash flow your portfolio actually produces.
- You want a close that keeps pace with your contract, often two to three weeks.
Key parameters
The shape of the program in plain terms. Exact numbers depend on the lender and the deal.
How a DSCR loan comes together
Talk through the deal
The property, the rents, the timeline, and the goal. Bring your numbers; no paperwork required to start.
Price the property
MaryAnn runs the rent against the payment, compares programs across lenders, and comes back with real options.
Choose the structure
Vesting, term, prepayment, and cash-out amount, each explained in plain terms before you commit.
Close on schedule
She coordinates lender, title, and agent, and most DSCR files close in about two to three weeks.
DSCR, answered
The questions investors ask most about DSCR loans. Anything else, just call or text.
What is a DSCR loan?
A DSCR loan qualifies an investment property on the rent it produces rather than your personal income. In most cases no tax returns or W-2s are required, and the property can close in an LLC.
How is DSCR calculated?
Monthly rent divided by the full monthly payment: principal, interest, taxes, insurance, and association dues. A ratio of 1.0 means the rent covers the payment; each lender sets its own minimum by program.
Do I need tax returns or W-2s?
In most cases, no. DSCR loans are underwritten to the property’s income as business-purpose loans, so personal income documentation is usually not part of the file.
Can I close in an LLC or other entity?
Yes. Business-purpose investor loans can close in an LLC or other approved entity, subject to lender guidelines. MaryAnn will walk you through the trade-offs of entity versus personal ownership.
Does DSCR work for short-term rentals?
Many DSCR programs can use short-term rental income; how it is counted varies by lender and program. Bring your numbers to the first conversation and MaryAnn will tell you what fits.
What states do you work in?
Business-purpose investor loans are available in most states, and it depends on the property state and program. Ask about yours in the first conversation.
Run your numbers.
Call or text MaryAnn directly, or schedule a time that works for you. Bring the rents and the plan; leave with real options.
Ready to apply? Start your application online (opens in a new tab)